A Broad View of What Constitutes a Bank

In today’s column Paul Krugman (“It’s a Miserable Life,” The New York Times, 20 August 2007) points out an interesting aspect of the current financial crisis:

The key to understanding what’s happening is taking a broad view of what constitutes a bank. From an economic perspective, a bank is any institution that offers people liquidity — the ability to convert their assets into cash on short notice — while still using their money to make long-term investments.

…

Consider the case of KKR Financial Holdings, an affiliate of Kohlberg Kravis Roberts, a powerhouse Wall Street operator. KKR Financial raises money by issuing asset-backed commercial paper — a claim that’s sort of like a short-term C.D., used by large investors to temporarily park funds — and invests most of this money in longer-term assets. So the company is acting as a kind of bank, one that offers a higher interest rate than ordinary banks pay their clients.

It sounds like a great deal — except that last week KKR Financial announced that it was seeking to delay $5 billion in repayments. That’s the equivalent of a bank closing its doors because it’s running out of cash.

The problems at KKR Financial are part of a broader picture in which many investors, spooked by the problems in the mortgage market, have been pulling their money out of institutions that use short-term borrowing to finance long-term investments. These institutions aren’t called banks, but in economic terms what’s been happening amounts to a burgeoning banking panic.

Mr. Krugman points out that while the banking industry narrowly defined is well regulated — that is, both brought under law and made more uniform and predictable — by a host of institutions — the FDIC, the Federal Reserve, various banking laws, the Basil accords, et cetera — these other bank-like institutions are not similarly covered. Hence, the Fed can modify its rates all it wants and the FDIC may offer insurance, but these don’t effect the pricing of asset backed securities or the willingness of investors to purchase commercial paper in anything like the way that they effect regular banking.

Just as the financial sector innovates, so regulation and governing institutions should innovate as well. Unfortunately the sort of consensus that produces institutions like the Federal Reserve or the FDIC come only out of major crises — not the sort at which we are currently looking. For that, the financial system will have to build up a lot more pressure.

State Resource Acquisition

As long as I am kicking Thomas Barnett, I should mention his article on the creation of AfriCom in the July issue of Esquire (“The Americans Have Landed,” Esquire, vol. 148, no. 1, July 2007, pp. 113-117, 134-137). It generated a bit of attention when it first came out (e.g. Plumer, Brad, “Surging Into Africa” and “More on Africa Command,” both 24 July 2007; Farley, Robert, “Africom,” TAPPED, The American Prospect, 24 July 2007; Yglesias, Matthew, “Africa Command,” The Atlantic.com, 24 July 2007).

Mr. Barnett pushes around a few theories about why AfriCom, but dismisses my own (“AfriCom: The New Scramble for Africa,” smarties, 1 May 2007) with some hand-waving:

There’s oil here, but the United States would get its share whether Africa burns or not, and it’s actually fairly quiet right now.

The Chinese are here en masse, typically embedded with regimes we can’t stand or can’t stand us, like Sudan and Zimbabwe. But the Chinese aren’t particularly liked in Africa and seem to have no designs for empire here. Beijing just wants its energy and minerals, and that penetration, such as it is, doesn’t warrant Africa Command, either.

The theory by which Mr. Barnett dismisses the idea that AfriCom is an economic-strategic countermove against China is that it’s unnecessary because we can all get access to the recourses we demand through the market. The problem with too facile a dismissal of this theory is that states have never wholly committed themselves to one theory of resource acquisition.

Throughout most of history governing institutions have been mercantilist and have lived by beggar-thy-neighbor. The way that a state and its clients acquired resources was by seizing them. It was only with the advent of modern liberalism that a firm division between the state and the economy emerged, but it was a slow process and up through the Second World War many a state pursued a policy of economic expansion through conquest. It was widely believed by many liberals that imperialist and economic competition was the cause of the First and Second World Wars. Hence at the end of the Second World War the United States decided to root out imperialism and replace it with a global system of open markets. Henceforth states would get out of the business of resource acquisition and it would be an entirely private activity conducted through the peaceful means of the market, not conquest. Roosevelt hated imperialism and sought to smash the European and Japanese colonial empires and made decolonization a central mission of the United Nations. Also GATT and the belated WTO were to be integral parts of this new liberal international system on par with the United Nations, the IMF and the World Bank, to prevent war and ensure smooth, open economic access — missions perceived as integral to one another by Roosevelt and his men.

But this liberal vision was a utopian fantasy of a sort in that states were never about to wholly abandon the economic foundation of their strength — and hence their survival — to the vagaries of the market. So states have wavered between theories of resource acquisition: open markets versus conquest.

The United States has been the most advanced liberal state and in the Twentieth Century became the guarantor of system of open markets. The majority of the military actions of the United States have been in support of this global system of markets. Nearly all of its interventions in Central America have been over worries that some critical resource was about to be removed from apolitical market access by a populist socialist. The U.S. intervened in Second World War Europe — among other reasons — to prevent Hitler from doing to the United States what Napoleon attempted to do to England with his continental system. The U.S. tempted Japan to war because it was unthinkable to the U.S. and other interested parties that Japan should monopolize the resources of half the Pacific rim and half of Asia. For nearly inverse reasons the United States went to war in Vietnam because it recognized — as demonstrated by Japan’s behavior leading up to the Second World War — that Japan’s economic interest in Southeast Asia was too significant for the resources of that region to fall behind the iron curtain (there were two contending world systems at that time). The First Gulf War was to prevent the emergence of too powerful an oil monopoly — sort of the Pentagon doing to greater Iraq what the FCC did to Ma Bell in 1982.

The United States is not about to trust its economic wellbeing to serendipity: it’s going to manage it — and that means a lot of things, but one thing that it means is the military. But the United States is acting — in part — on behalf of the liberal international order. That the U.S. is required to intervene as much as it does — or perceives that it has to — suggests that a lot of states the world over still want to lapse from the open market back to conquest as a means for laying hand on their necessities. On the other hand, perhaps the U.S. is a player, only posing as the referee the better to play (Calvinball?).

In Africa it may be the case that the liberal order can provide everyone what they want — or at least everyone doing the divvying up; whether the parceling of Africa’s resources will have any benefit for the Africans themselves remains to be seen. But no state — not even the primary advocate and guarantor of the liberal international order — is about to stake its future on the hope that unfettered market access is going to play out in a straightforward way (I’ve written about this before; see “China’s Strategy for Resource Competition,” smarties, 30 March 2005, bullet two). Even in this world of open markets — or especially in this world of open markets — sanctions and economic exclusion have always played a role. So states make nice and play the diplomatic game of tit-for-tat, preparing to clamp down should the time come. Favors are proffered and chits collected — for a rainy day. A few military bargains will be struck and maybe some men and hardware will be put in place so that everyone knows how things stand. No state is going to idle while a positive sum game plays out against its favor. In the event of a crisis, states are either the quick or the dead. In Africa what we are seeing is the laying out of the pieces on the board and the early maneuvers.

Public Financial Institutions

Thomas Barnett is conservative leaning and — ironically enough — is one of those intellectuals who is stupid in exactly the way that conservatives predict intellectuals to be: he tends to trip over his own intelligence. A perfect example is his completely incoherent take on the recent, sudden burst of the housing bubble (“Nice analysis of the sub-prime ‘crisis’,” 13 August 2007):

The only crisis I see coming out of the subprime shenanigans (such new tricks to fleece people will always be with us) would involve governments assuming they should bail out all those hedge funds that long dabbled in this stuff. O’Driscoll makes a great comparison to the S&L crisis of years ago: so long as financial institutions assumed the FDIC bailout was coming, they’d pawn off the risk to the government instead of effectively discounting it themselves.

Really? The only crisis he sees is moral hazard? So we’re courting moral hazard toward no specific end?

Government intervention isn’t bailing out “all those hedge funds”: it is protecting the rest of us — not necessary culpable in the “shenanigans,” but still subject to the consequences thereof — from spreading economic misery. To suggest that this same old moral hazard argument that economic conservatives have been making since 1913 is somehow penetrating analysis of our present day woes is completely retrograde. Moral hazard is real, but people with less pronounced agendas have a lot more interesting things to say about the subject than that in the face of it we should do nothing.

The FDIC, the Federal Reserve, the SEC, punitive, but stabilizing taxes, transparency laws, etc. were created specifically because “foolish” investors engaging in “shenanigans” could be found well before any of these public sector economic institutions ever existed; and further, to protect non-privileged investors who did everything by the book from said “shenanigans” — in other words, to prevent the spread of irrationality. Once a critical mass of people begin to act irrationally — e.g. in a financial panic — rationality flips and the irrational becomes the rational thing to do.

And as if this wasn’t disconnected enough, then there’s this parenthetical aside:

(since finance is–to a large part–a young man’s game, the bulk of the front-line players tends to age out every dozen years or so, which pretty much guarantees you new forms of shenanigans with the same regular frequency)

It’s all fine and good to use pejoratives such as “shenanigans” and “foolish” — as Mr. Barnett does — to describe less than perfectly rational market actors who continue to fall for plaid-out investment schemes such as the housing bubble long after their true nature has become more than apparent, but if less than perfectly rational behavior is in fact systematic, as Mr. Barnette suggests with this theory, then what’s the point of moralizing about it? Systematic problems should be dealt with through systematic solutions — and not systematic solutions that entail mass suffering for all of society.

The Federal Reserve and Mortgage Backed Securities II

So it turns out that what was unusual about the Friday open market operations of Federal Reserve was even more narrowly technical still. The Federal Reserve always accepts mortgage backed securities as collateral, but usually issues loans backed by this sort of collateral at a less favorable rate. What was unusual on Friday was that the Federal Reserve issues all loans at the most favorable rate, no matter the collateral.

Kevin Drum passes along an e-mail from Stephen Spear, a professor of economics at Carnegie Mellon University, in which the Professor relates a conversation with a Federal Reserve colleague about the operation (“Friday’s Liquidity Event,” Political Animal, The Washington Monthly, 12 August 2007):

Here’s what I’ve been told by a colleague at the Fed:

First a minor point: Most of the open market operations that the Fed does (including Friday’s) are short-term collateralized loans and not outright purchases of securities. Friday’s loans were all overnight (well, over the weekend, actually, maturing on Monday). So the Fed is technically not buying anything; it’s been making short-term loans of cash against collateral.

The Fed accepts three categories of collateral for these loans. One is Treasury securities, another is other government agency securities, and the third is mortgage-backed securities that are federally guaranteed. Because they are federally guaranteed, the mortgage-backed securities the Fed accepts are (obviously) the very best.

Typically the interest rate on these short-term loans varies slightly depending on the type of collateral offered by the borrower. Treasuries get the lowest rate; mortgage-backed securities the highest. (The details of the last 25 OMOs, including the rates for each type of security, are available here.)

What was unusual about Friday (other than the size of the operation) is that the Fed announced it would lend against all three types of collateral at the same rate.

To quote my Fed colleague on this: “I’m not sure why we did this. I think the idea was that given the size of the operation we did not want to risk disrupting the Treasuries markets, but there may have been other motivations. The expectation was that borrowers would primarily use mortgage-backed securities, since these have the lowest opportunity cost to the borrower.”

On the web page above, you will see that for Friday’s operations, under collateral type it just says “mortgage-backed.” What this means is that mortgage-backed securities or any better securities were allowed as collateral — in other words, all three types were acceptable. Apparently, the media misinterpreted this as saying that the Fed was only accepting mortgage-backed securities, which led to the headlines about the Fed buying these things up.

So, the bottom line is that the Fed’s actions on Friday were unusual, but not tremendously so. It did three OMOs instead of the usual one. The quantity of reserves lent out was larger than normal, and the way collateral was handled was slightly unusual. But the general operating procedure, including the type of collateral accepted, was completely standard. It would seem that the media is trying to make the story a lot more sensational than it truly is.

Given the extraordinary amounts of money here along with tweaks to the usual policy, obviously the Federal Reserve sees a problem requiring extra-ordinary measures, but obviously not the panic initially reported by the press.

The Federal Reserve Does Not Buy Mortgage-Backed Securities

When I saw the following story in the New York Times on Friday (Peters, Jeremy W. and Wayne Arnold, “Stocks Are Volatile After Global Sell-Off,” 10 August 2007) I fucking freaked:

The E.C.B. injected another 61 billion euros ($84 billion) into the banking system, after providing 95 billion euros the day before. The Federal Reserve today added $19 billion to the system through the purchase of mortgage-backed securities, then another $19 billion in three-day repurchase agreements. The Fed added $24 billion on Thursday.

It’s not the amounts of money that are unusual. Yes, this indicates a fairly aggressive attempt to preserve liquidity in financial markets and it is definitely earning the headlines it is getting in The Financial Times and The Wall Street Journal. But that the Federal Reserve might engage in the direct purchase of $19 billion worth of mortgage-backed securities would indicate a real problem and the adoption of extraordinary, panic measures on the part of the Federal Reserve. On Friday I was thinking how I might reinvest my 401k into gold doubloons.

Thankfully, on Saturday Dean Baker pointed out (“The Fed Does Not Buy Mortgage-Backed Securities!!!!!!,” Beat the Press, 11 August 2007) that this was just incompetence on the part of the economic reporting at The New York Times and The Washington Post (who also reported the story). That what really happed was that the Federal Reserve made a more routine loan through the discount window and accepted the $19 billion in mortgage-backed securities as collateral for the loan.

While you’re there, his post (“Tell The Post: The Problem Isn’t Subprime,” Press, 11 August 2007) pointing out that the cause of our current financial woes is not the subrime market (dirty, irresponsible poor people) is a useful reminder. The real problem is the bursting of the housing bubble more generally. The subprime market is just the first place it’s really being felt.

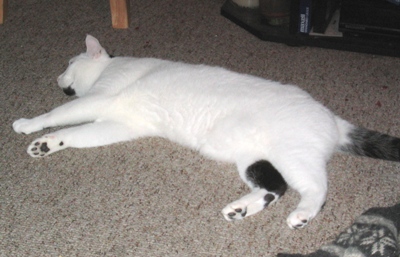
Friday Cat Blogging: Too Hot for Kitty

7 August 2007, Washington, D.C., lethargic Mowgli

The weather has been unbearably hot here in D.C. — though not yet topping out the thermostat for the region in August. I’ve often wondered how an animal with a fur coat permanently affixed to his back copes with this heat. It’s never seemed to pose a problem for kitty. I guess that he has a much smaller mass-surface area ratio than me. But this year even he seems to be feeling it. He has been doing a lot of flopping, laying around and generally looking miserable.

Where Your Boots Go, There Your Mind Will Be As Well

I think the proper way to think about our situation in Iraq is this. It may be true that many vile consequences may ensue in Iraq should the United States withdraw. But the options aren’t that the U.S. armed forces save Iraq from itself versus U.S. soldiers go back to sipping cool lemonade in the backyard. It’s entirely possible that the choice is between staying in Iraq or preventing the next September 11th.

Al Qaeda and their ilk have a grand strategy. They are not going to match their weakness against our strength. This is not the Fedayeen Saddam. They are not about to try to engage the Fourth Mechanized Infantry in Toyota pickup trucks. The Liliputian terrorists will bind Gulliver, overwhelm us with distractions, mire us in a series of diversions. Having no commitments, no obligations of their own, they will then match the nimbleness of al Qaeda against the encumberment of the United States. As Osama bin Laden himself has said, “All that we have to do is to send two Mujahideen to the furthest point East to raise a piece of cloth on which is written al-Qaida, in order to make the generals race there to cause America to suffer human, economic, and political losses without their achieving for it anything of note …”

My ever so slight sampling of the zeitgeist says that we are working our way toward a condition — material and of mind — not unlike that in the late 1990s and early 2000s as the country slouched toward September 11th. Dangerous and anarchic regions of the world are spreading, extremists are gathering strength, plots — one can imagine — are unfolding. Nothing less than the most recent NIE has suggested that the terrorist threat is growing, not waning, and that al Qaeda is gaining strength. Just as after the Cold War the United States was unable to heed the warning of both events and the prognostications of certain elites, so George Bush has the put the country into a trance of Iraq focus. Despite a changing threat profile, we can’t think about anything else. Already al Qaeda and Co. have pivoted. New threats are in the making, but mired in the thought of post-September 11th and Iraq — the irony here is too much — we are incapable of conceptualizing or doing anything to prevent the next September 11th.

The right has argued that in the post September 11th world, the old Cold War system of long-term alliances like NATO is obsolete, that the United States needs to remain nimble, to rely on ad hoc coalitions of the willing. And yet in Iraq the United States has permanently bound itself in a coalition of the compulsory. That broken statue of Hussein was the signing ceremony and there is no nullification clause in the treaty. In Iraq the United States stepped into a bear trap and it closed on our foot. It’s going to hurt and it’s going to be bloody, but its time to gnaw that foot off and hobble free — before the trapper comes to claim our pelt.

Seize the Opportunity to Throw One Back

I’m considering educating myself a little on Graham Greene and so, at the inspiration of a passage posted by Andrew Sullivan (“‘The Torturable Class’,” The Daily Dish, 26 July 2007), purchased a copy of Our Man in Havana. Christopher Hitchens wrote the introduction and — apropos an earlier post (“Booz-Hound Christopher Hitchens,” 28 June 2007) — he tells the following tale:

Graham Greene famously subdivided his fictions into ‘novels’ and ‘entertainments’ …

I should like to propose a third, or subcategory: the whisky (as opposed to the nonwhisky) fictions. Alcohol is seldom far from the reach of Greene’s characters, and its influence was clearly some kind of daemon in his work and in his life. A stanza of that witty and beautiful poem ‘On the Circuit,’ written in 1963, registers W. H. Auden’s dread at the thought of lecturing on a booze-free American campus and asks, anxiously and in italics:

Is this my milieu where I must
How grahamgreeneish! How infra dig!
Snatch from the bottle in my bag
An analeptic swig?

Describing a visit to a 1987 conference of ‘intellectuals’ in Moscow in the early Gorbachev years, both Gore Vidal and Fay Weldon were to record Green making exactly this dive into his bottle-crammed briefcase.

Makes me think, as Nietzsche said, that all writing is autobiographical of a sort.

Cool Dude

With the publication of his latest, Thomas Paine’s Rights of Man, Christopher Hitchens has acceded to the rank of author whose photograph is promoted from the back inside flap to displace a more topical graphic from the cover. Some authors you can understand why they go on the cover. Ann Coulter is at least hot (as right wingers go) and can be expected to move some copies, more to be admired than read. Christopher Hitchens, on the other hand, is like the Archie Bunker of the left. But I guess he’s a man whose image is an icon at this point though.